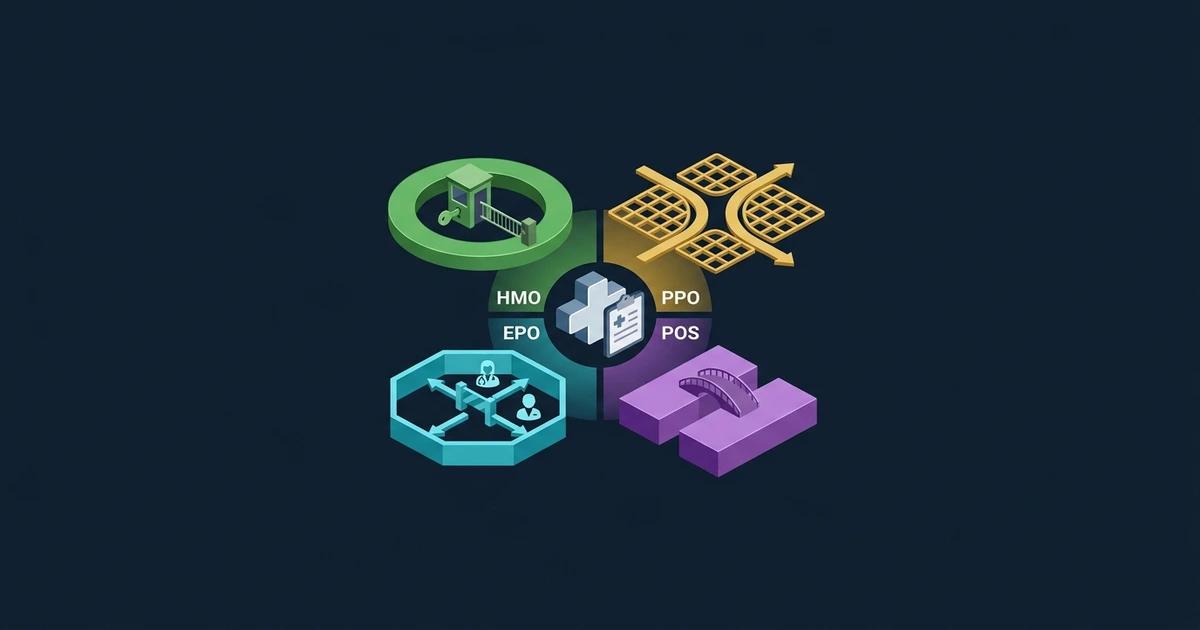
HMO, PPO, EPO, and POS are four ways a health plan can organize access to doctors and hospitals. On a licensing exam, the letters matter less than the rules behind them: Can the member see an out-of-network provider? Is a primary care doctor involved? Is a referral needed for a specialist? A scenario question usually turns on one of those details.
The broad patterns are useful, but an actual policy controls its own benefits. Network design and referral rules can vary by product and state. For exam preparation, learn the standard model first, then read the wording in the question. The federal HealthCare.gov guide to plan types is a helpful reference for the common distinctions.
Begin with the network question
A provider network is the group of doctors, hospitals, and other providers that have contracted with a plan. A member may pay less when using that network. The four plan types differ mainly in how much coverage remains when the member goes outside it and how care is coordinated inside it.
If an exam question says a member can visit a doctor outside the network for covered, non-emergency care but will pay more, think of a PPO or a POS plan. If it says non-emergency out-of-network services are generally not covered, think of an HMO or EPO. Then look for the referral clue to narrow the answer. Emergency care is an important exception; do not turn the general network rule into an absolute claim about every emergency service.
HMO: coordinated care within a network
A health maintenance organization usually limits coverage to care from providers who work for or contract with it. Non-emergency out-of-network care is generally not covered. HMOs often emphasize coordinated and preventive care. Many require a member to choose a primary care physician, who coordinates treatment and may provide referrals to specialists. The exact referral rule is set by the plan, so “every HMO always requires a referral” is too broad.
Picture a member who wants to see a dermatologist. Under a traditional gatekeeper HMO, the member begins with the primary care doctor and gets a referral to an in-network specialist. An exam answer describing unrestricted visits to any out-of-network dermatologist at a higher cost would not match the usual HMO pattern. If the question explicitly gives different policy terms, however, use those terms.
PPO: more provider choice, different costs
A preferred provider organization encourages network use by charging less for in-network care. Members can generally use out-of-network providers for covered services without a referral, but they pay more. Out-of-network deductibles, coinsurance, and possible balance billing can make that choice expensive. The key exam distinction is that a PPO offers a coverage path outside the network, unlike the usual EPO or HMO model.
Think of a member who has an established physician outside the network. A PPO may still contribute toward a covered visit, though the member’s share will be higher. Do not mistake “covered” for “costs the same.” When a scenario mentions both freedom to choose and a financial incentive to stay in network, PPO is often the best fit.
EPO: network boundary with less gatekeeping
An exclusive provider organization usually covers services only when the member uses its network, apart from emergencies. That makes its network boundary resemble an HMO’s. In common EPO designs, members do not need a primary care gatekeeper or referrals to see in-network specialists. The combination—strict network, easier specialist access within it—is what makes an EPO distinct in many exam questions.
Suppose a member can book an in-network cardiologist directly but would not have routine care covered at an out-of-network clinic. EPO is a strong possibility. Still, verify the details the question gives you. Real plans may have prior authorization rules even when they do not require a PCP referral; those are different requirements.
POS: the point of service changes the cost
A point-of-service plan combines features of network-based coordinated care and out-of-network choice. Members pay less using in-network providers, and a referral from a primary care doctor is commonly required to see a specialist. They can generally go out of network for covered services at a higher cost. The name reflects that the member’s choice at the point of service affects how benefits are paid.
For an exam scenario, the combination of a PCP referral and an out-of-network benefit is the distinctive clue. A question that says “referral required, but the member can still see an outside specialist at greater cost” is pointing away from the standard HMO model and toward POS. Compare the exact policy terms if multiple answers look plausible.
How to solve a plan-type question
Rather than trying to memorize four long definitions, read the question in this order:
- Is non-emergency out-of-network care covered? If yes, PPO or POS becomes more likely. If no, HMO or EPO becomes more likely.
- Does the member need a PCP referral for a specialist? A referral points toward a traditional HMO or POS structure; direct access points toward PPO or EPO.
- What happens to the member’s costs? A higher out-of-network share can distinguish coverage with restrictions from no ordinary out-of-network benefit.
Be careful with phrases such as “no referrals” and “no prior authorization.” They are not synonyms. A plan might let a member book an in-network specialist directly while still requiring approval before a costly procedure. Also distinguish the network type from the metal level of a Marketplace plan. Bronze and Gold describe cost-sharing categories; they do not tell you whether a plan is an HMO or PPO.
Connect this topic to the rest of your health exam
Managed care questions sit alongside Medicare and other health coverage topics. Medicare Advantage plans can use HMO or PPO network designs, which is one reason the terms reappear in our Medicare, Medicaid, and Medigap guide. If you are still deciding which license exam to take, read combined versus separate Life and Health exams.
To test the distinctions, use the Health insurance practice test and then your state’s Life and Health page. When you miss a network question, identify the specific clue that changed the answer. The goal is not to recite letters; it is to understand what happens when a member chooses a provider.
Primary reference: HealthCare.gov, Health insurance plan and network types. Plan documents and state rules govern actual coverage; the patterns here are for licensing-exam study.